


Supabase vs. Vercel
 Jan-Erik Asplund
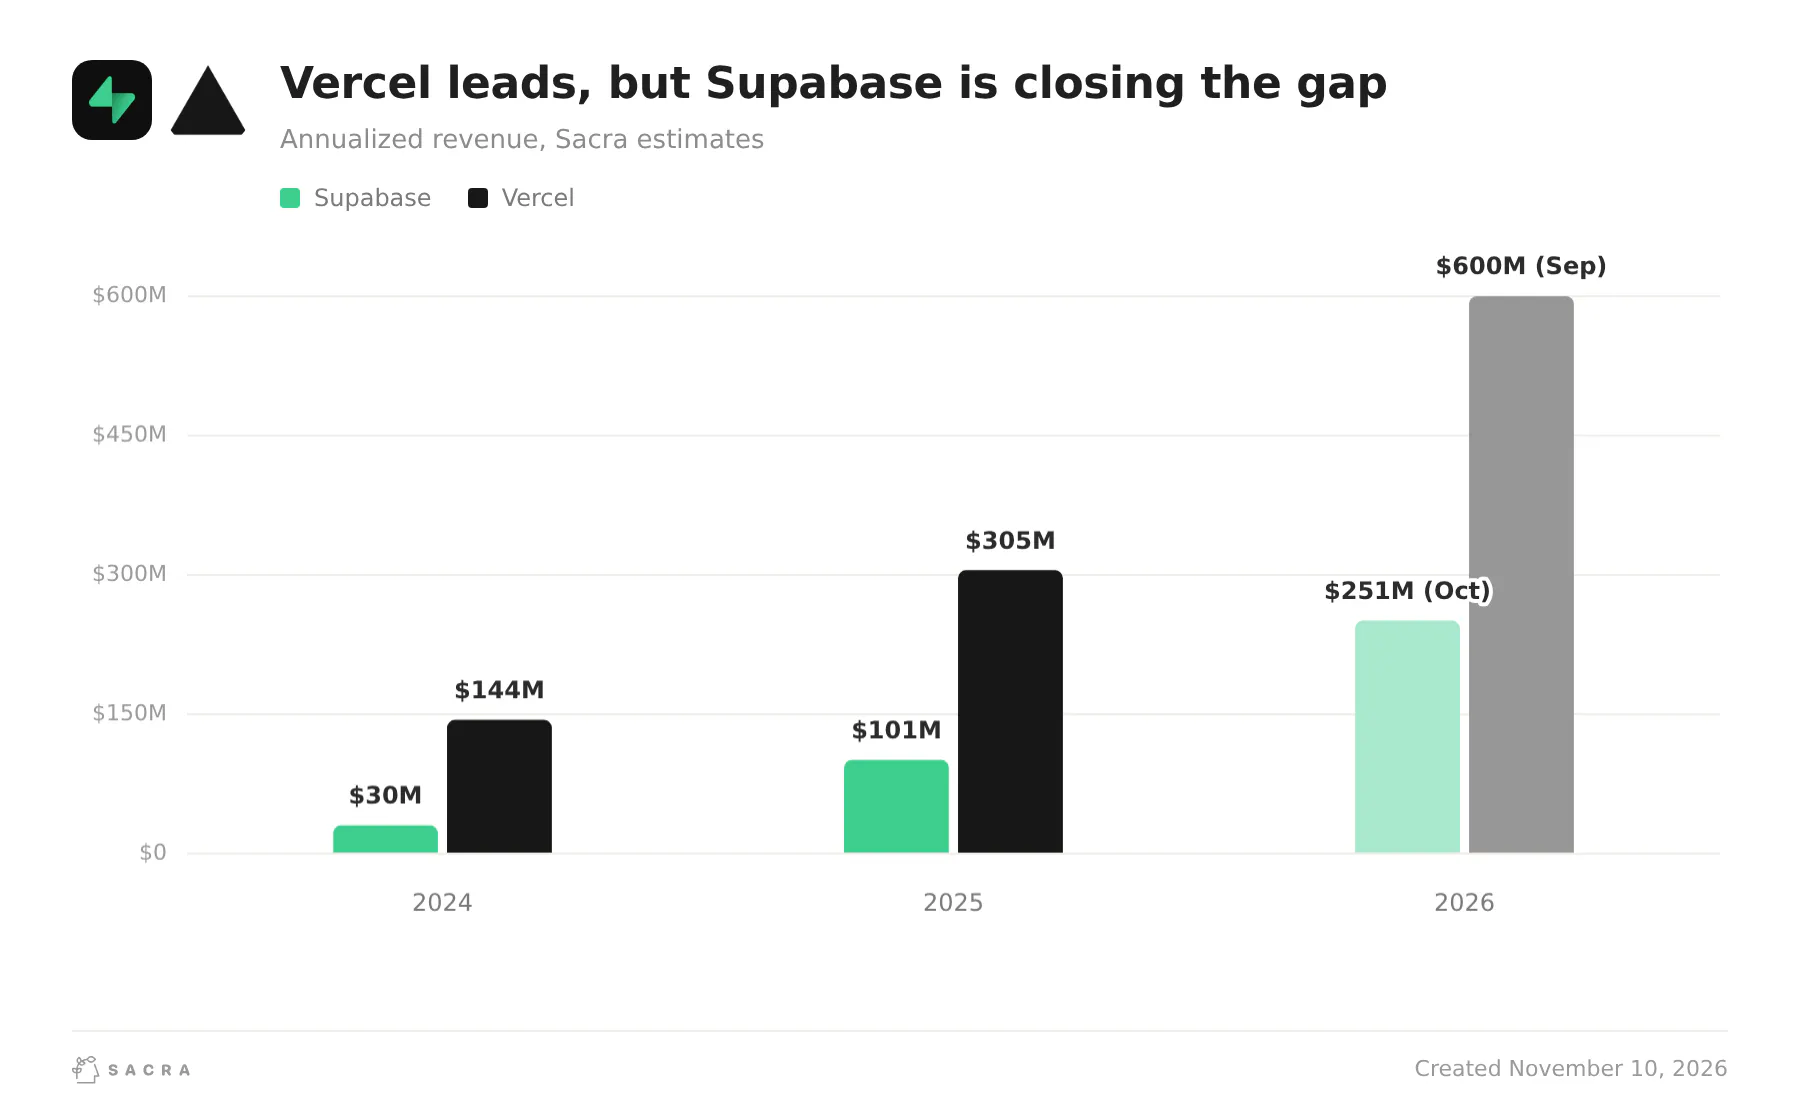
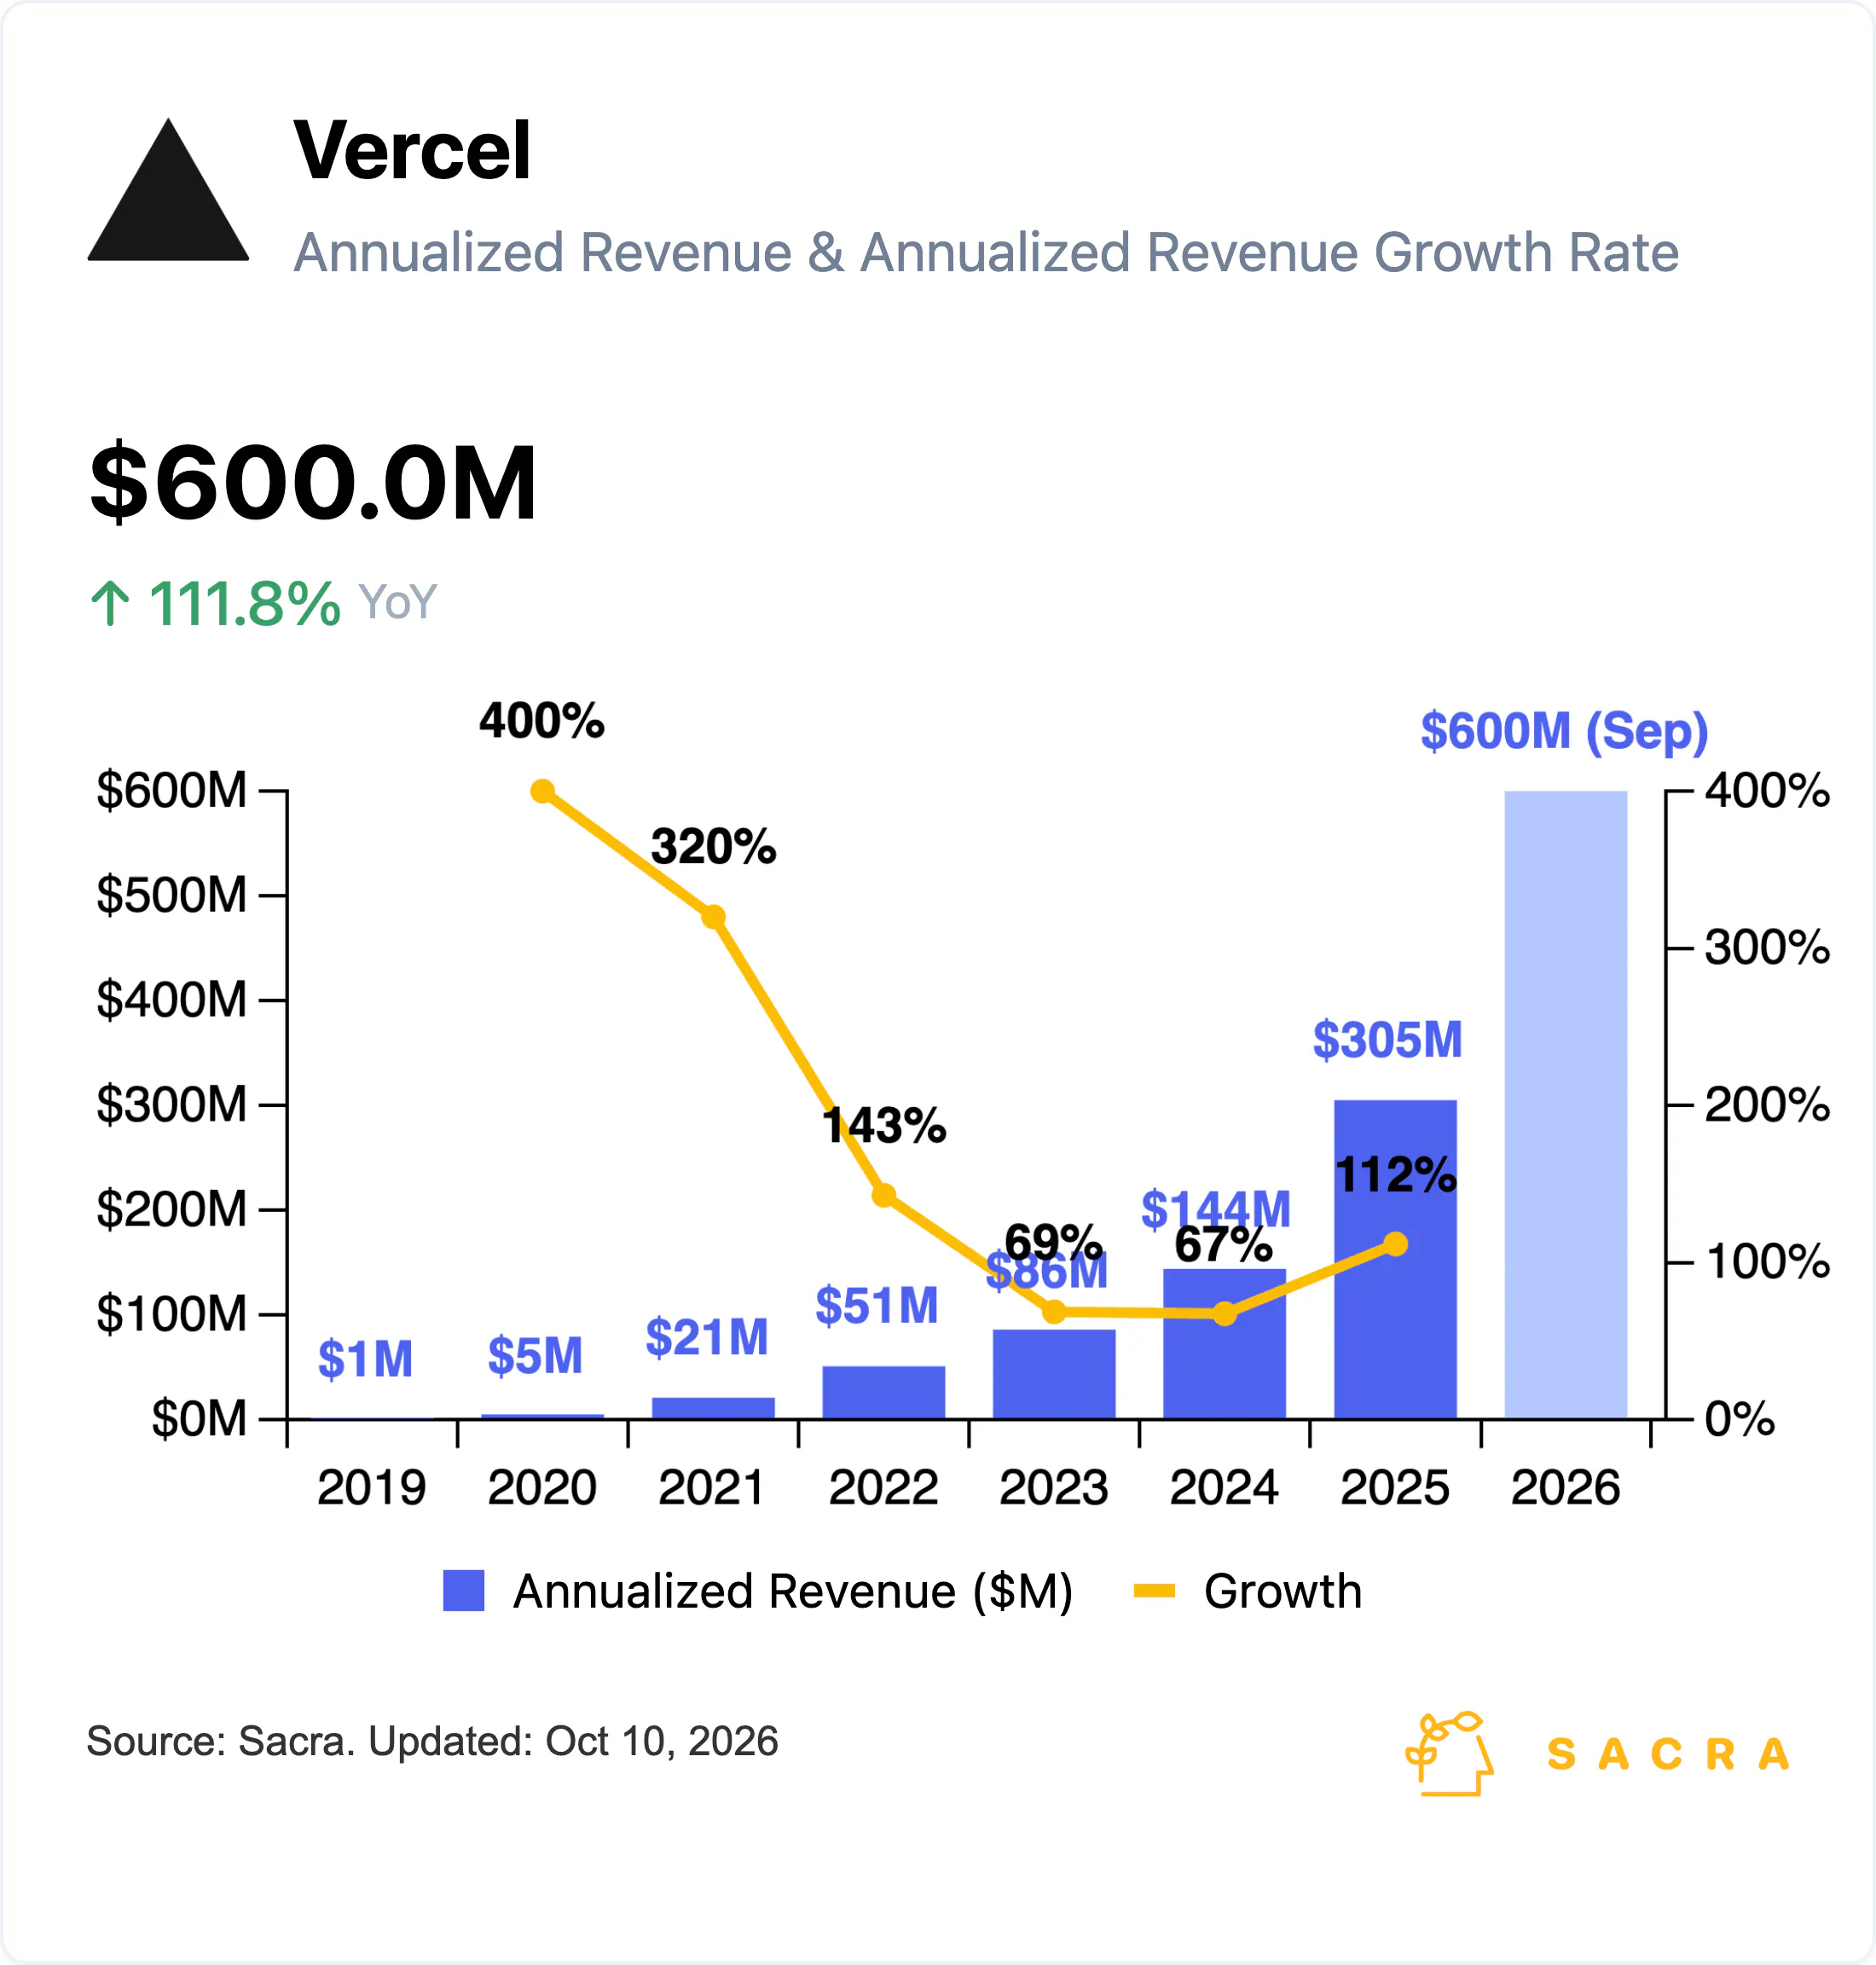
TL;DR: Supabase ($251M annualized revenue in October 2026) & Vercel ($600M annualized revenue in Setpember 2026) are competing to capture more of the spending behind AI-generated apps, expanding into each other’s territory across agent sandboxes & authentication. For more, check out our updated reports on Supabase (dataset) and Vercel (dataset).
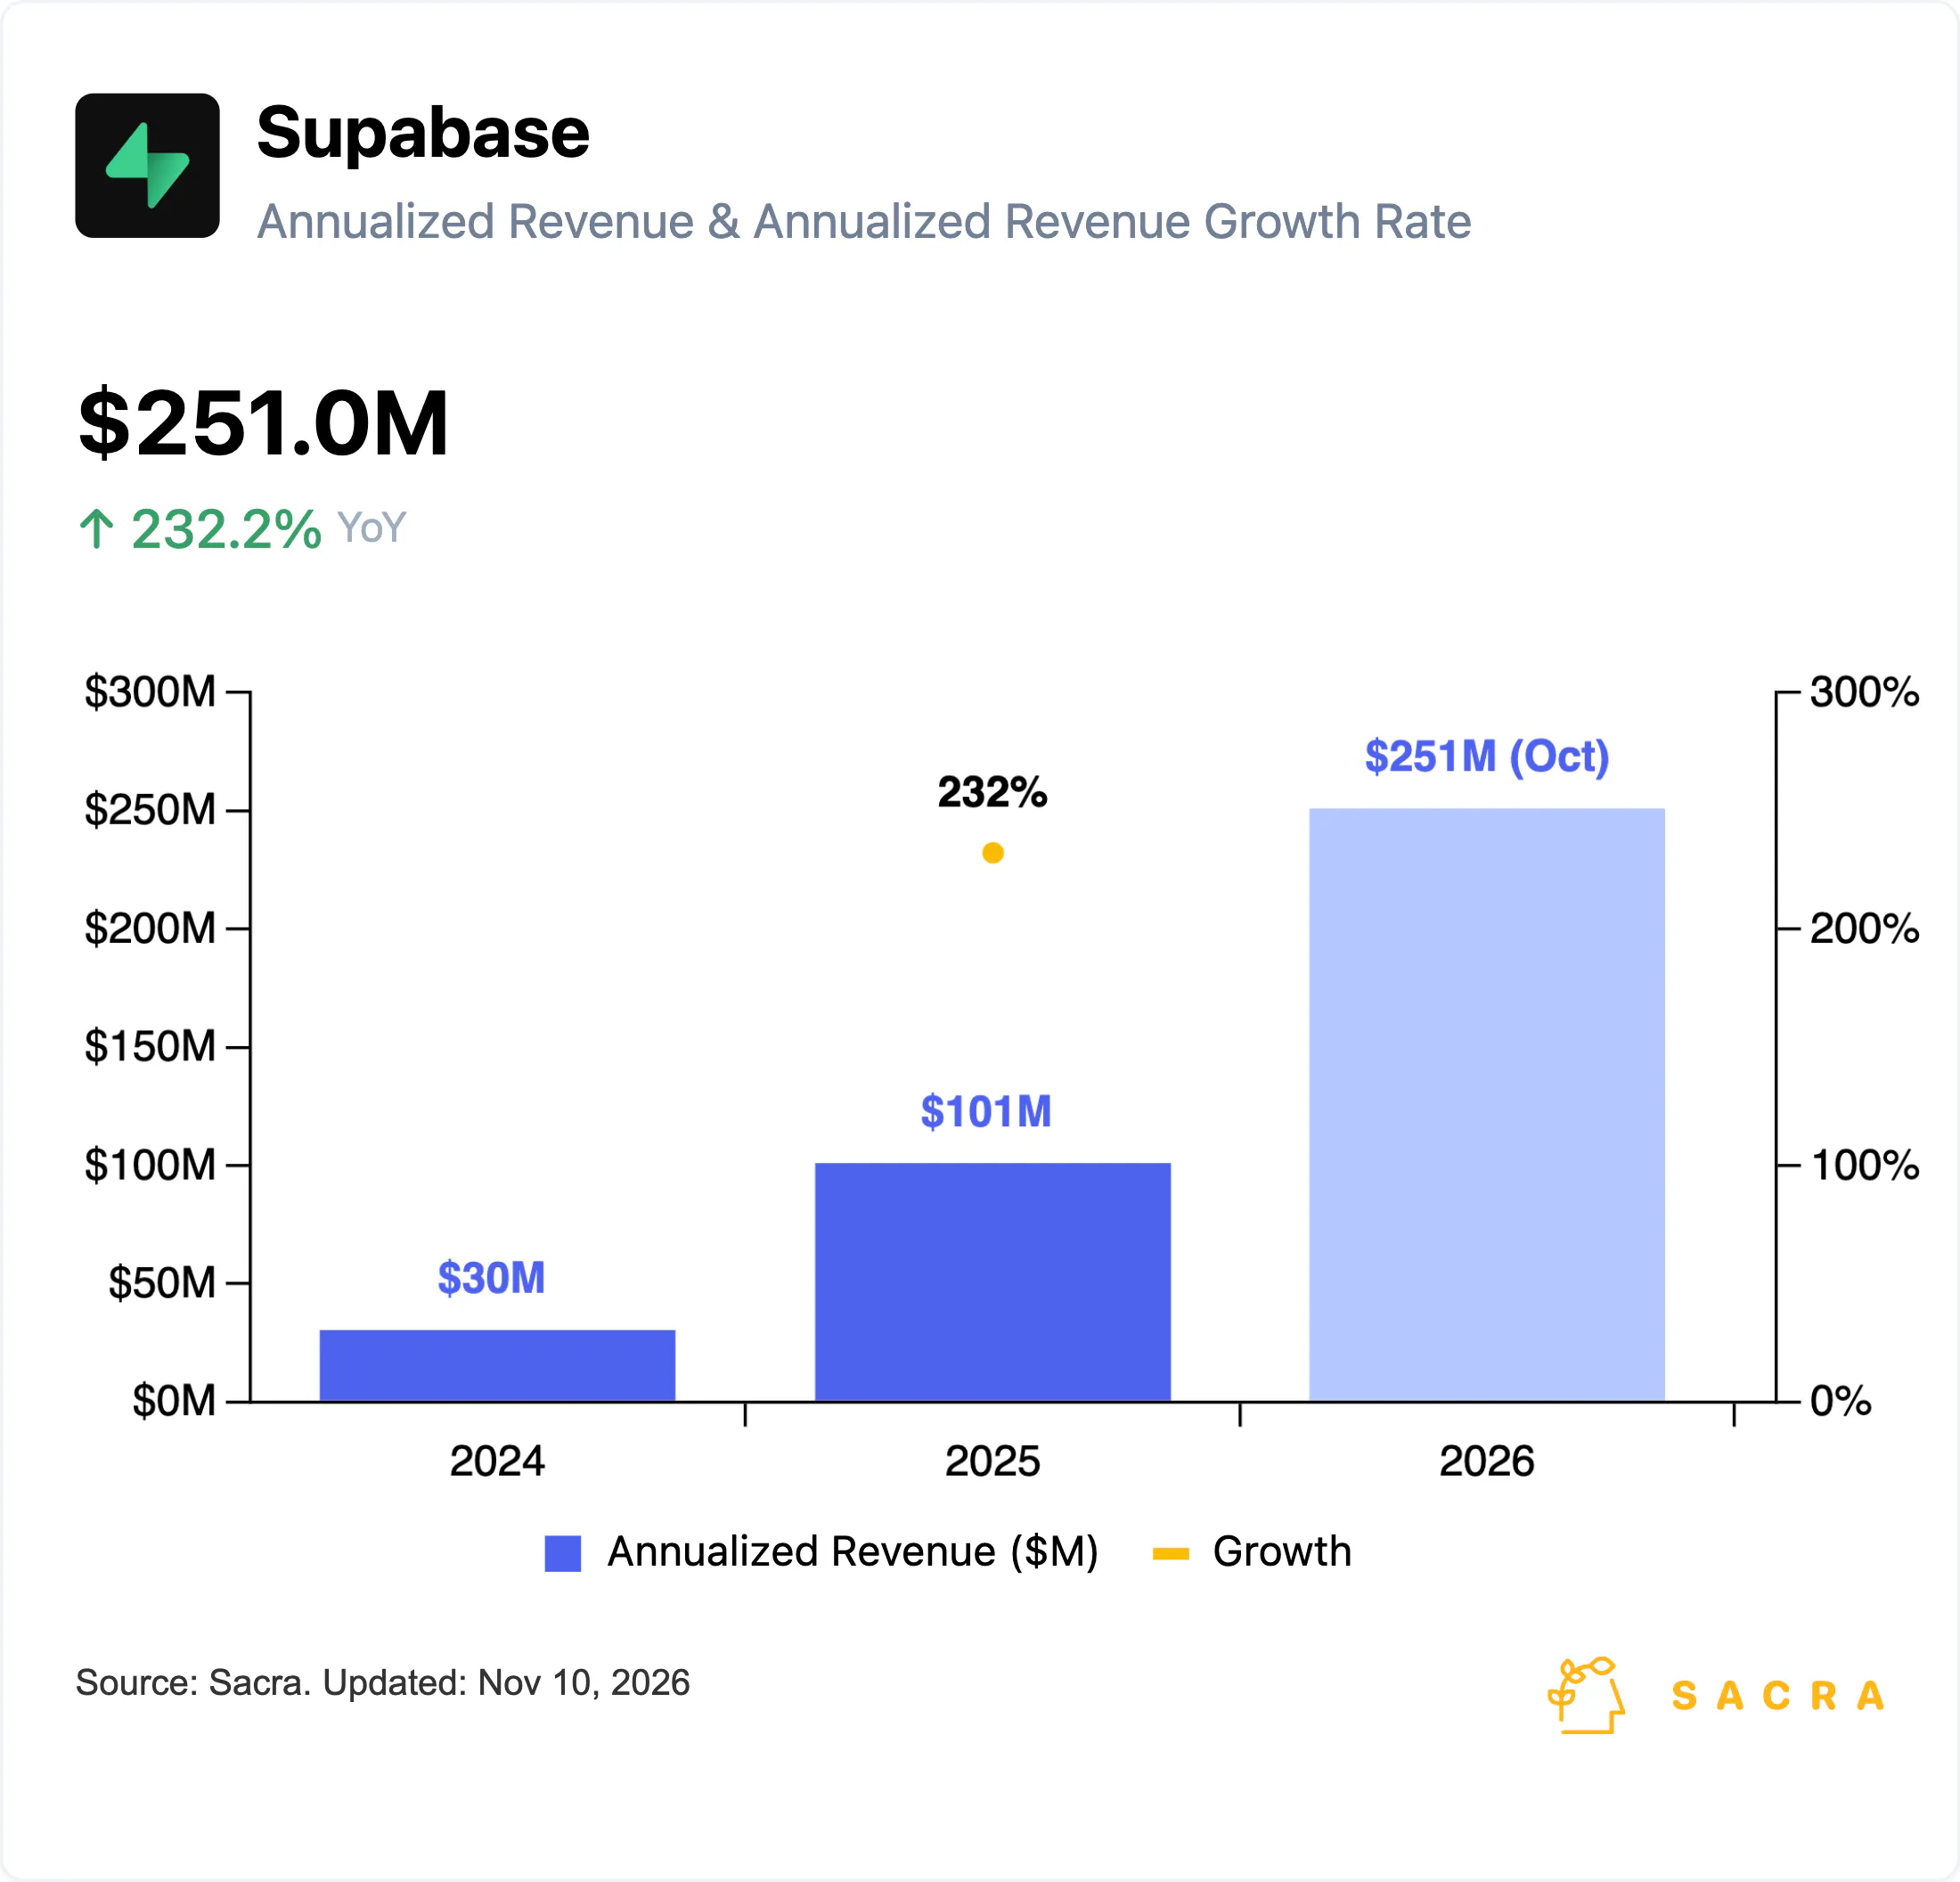
We first covered Supabase in October 2025 at $70M ARR as the default back-end for the vibe coding boom, and then again in June 2026 as the company passed $170M ARR on the back of explosive top-of-funnel growth.
Our Vercel coverage goes back to 2022 when we wrote about Vercel’s consumerization of developer tools alongside Netlify, then we followed up in May 2025 at $172M/year in revenue and again in August 2026 at $340M/year as AI coding became its main growth driver.
Key points via Sacra AI:
- Devtools are the bellwether for the AI-agent-as-the-buyer, as Anthropic’s Claude Code & OpenAI’s Codex increasingly make buying decisions on developer infrastructure, fueling Supabase’s 8.5x growth from a Sacra-estimated $30M in annualized revenue at the end of 2024 to $251M as of October 2026 and re-accelerating Vercel at $144M in annualized revenue, growing 67% YoY, to $600M as of September 2026, up nearly 2x in 2026 alone, with agents now initiating more than 50% of Vercel deployments and 70% of Supabase’s ~5M monthly database launches.
- Supabase & Vercel are colliding over ownership of the app, coming from opposite directions with Supabase starting from the backend and launching Supabase Compute (AI agent sandbox, October 2026) versus Vercel starting on the frontend & deployment and expanding into backend services with Vercel Sandbox (AI agent sandbox, January 2026) and its acquisition of Better Auth (user accounts & login, July 2026).
- Both at ~$10B in valuation, Supabase raised its $500M Series F led by GIC in June 2026 at roughly 62x its then-annualized revenue of $170M growing 221% YoY, compared to Vercel which raised its $300M Series F co-led by Accel & GIC 9 months prior in September 2025, at roughly 35x its then-annualized revenue of $265M, growing 82% YoY.
For more, check out this other research from our platform:
- Supabase (dataset)
- Vercel (dataset)
- Supabase at $170M/year growing 221% YoY
- Vibe coding's backend
- Supabase at $70M ARR growing 250% YoY
- Vibe coding index
- Replit (dataset)
- Replit passes $500M/year
- Lovable (dataset)
- Bolt.new (dataset)
- Lovable vs Bolt.new vs Cursor
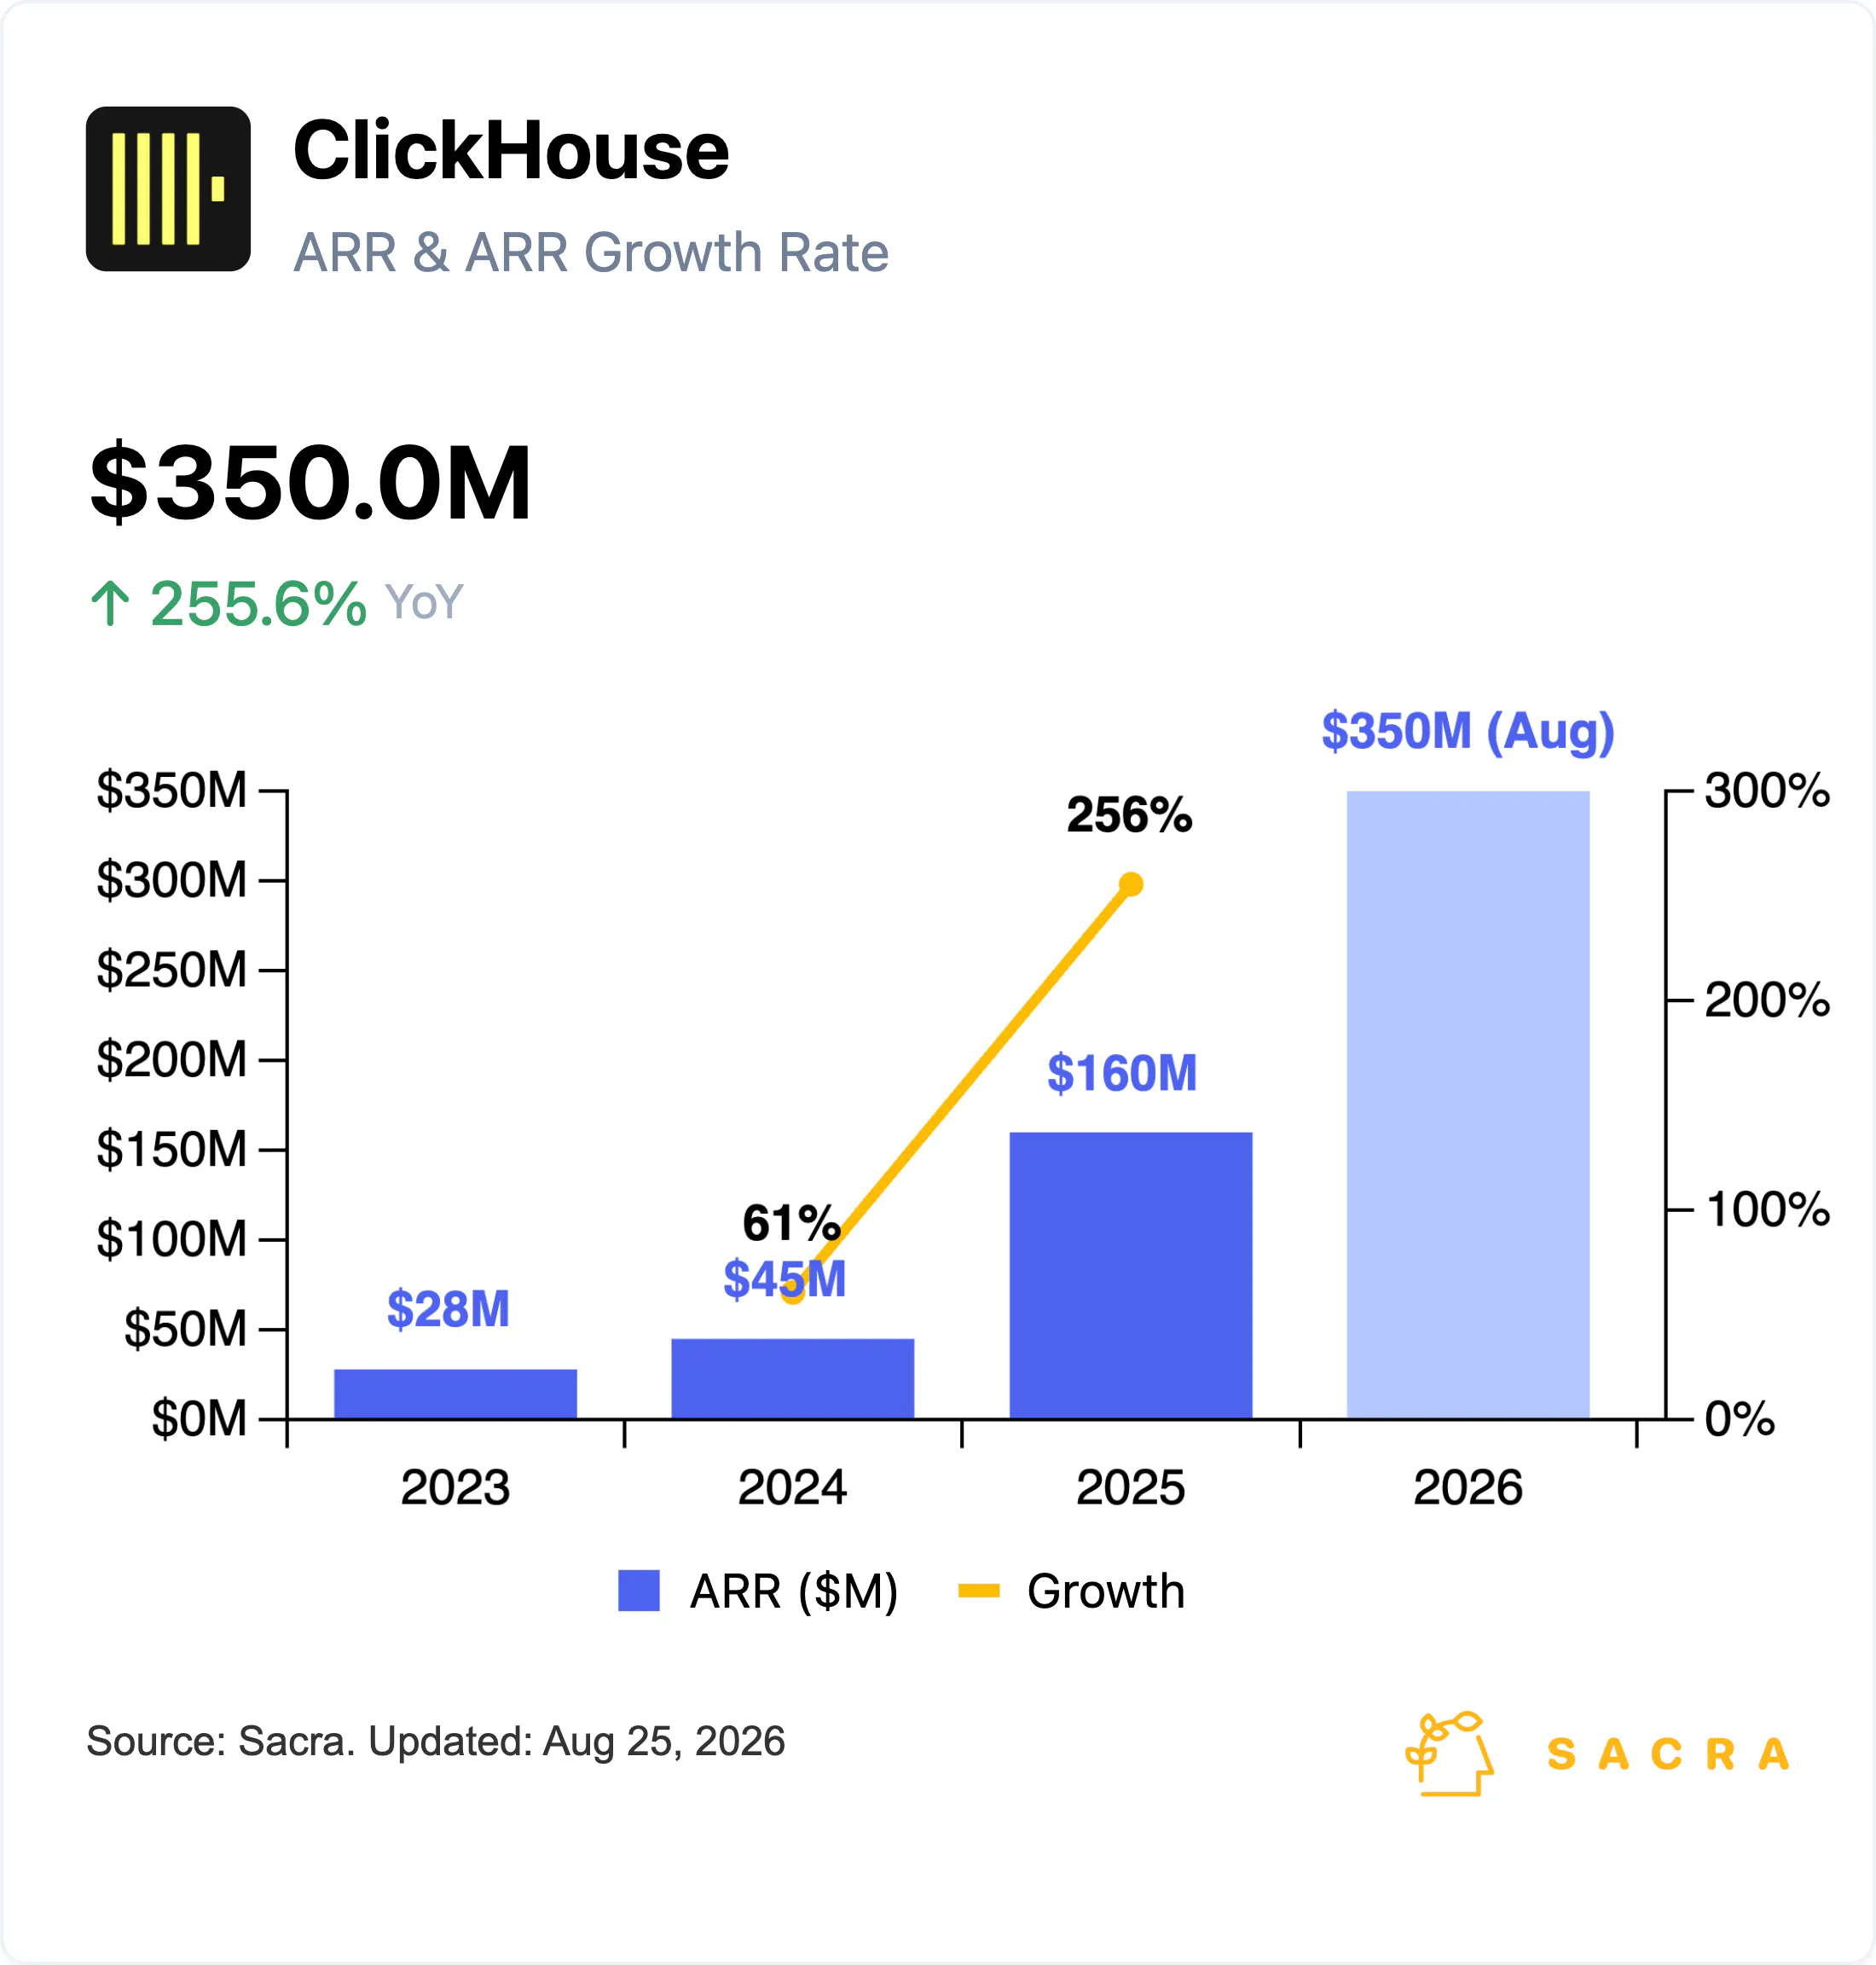
- ClickHouse (dataset)
- Product manager at Firebolt on on scaling challenges and ACID compliance in OLAP databases
- AI program manager at AstraZeneca on running self-hosted ClickHouse
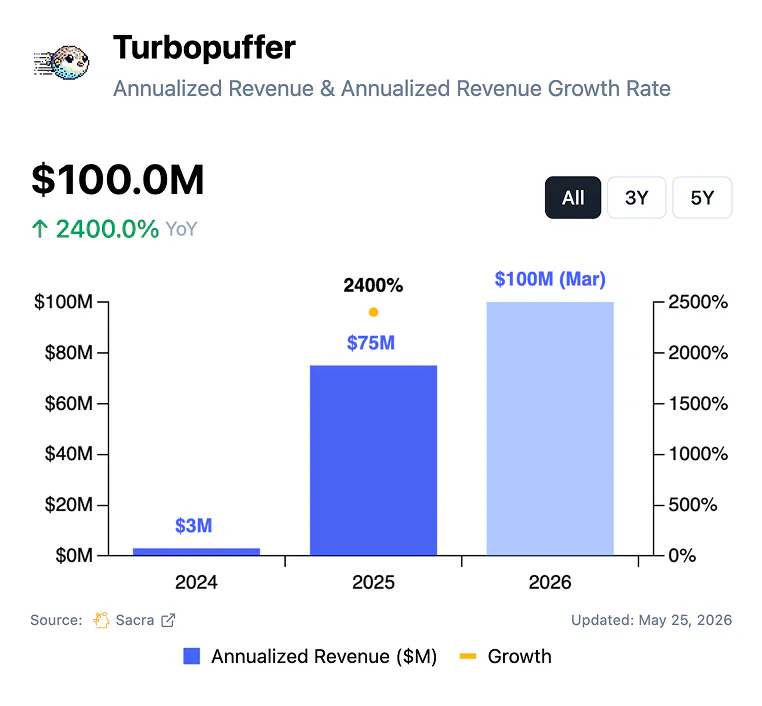
- Turbopuffer (dataset)
- $100M/year PostHog of vector databases
- Databricks (dataset)
- Databricks at $4.8B ARR
- Databricks at $4B ARR growing 50% YoY


